A bank account being frozen after a small online withdrawal can be confusing, especially when the amount is only ₹583. For ReddyBook readers who follow online gaming and payment-related news, such situations raise important questions about banking security, transaction checks, and account access. A user may believe that receiving a small payment is a normal activity, yet a bank can sometimes restrict an account when a transaction is linked to a wider financial review.
The amount involved may seem too small to cause concern. However, banks do not always assess transactions based only on their value. The source of the money, payment history, complaints, and instructions from authorities can also matter.
In this article, we will examine a reported scenario involving a ₹583 ReddyBook withdrawal and a frozen bank account. We will explain what a bank freeze means, why a small payment may become part of a larger investigation, and what users should understand before making assumptions.
Important: The specific ₹583 case has not been independently verified through bank records, a police notice, or other primary evidence available here. We will therefore treat it as a reported scenario, not as a confirmed finding that ReddyBook caused a bank freeze.
Our focus is on understanding the possible reasons behind such restrictions and the steps an affected account holder can take through official banking and legal channels.
Understanding the ₹583 ReddyBook Withdrawal Case
The situation described in the case is straightforward at first glance. A user reportedly received or requested a withdrawal of ₹583 associated with ReddyBook and later discovered that their bank account was frozen or restricted.
The natural reaction is to connect the two events. If the account was working before the withdrawal and stopped working afterwards, the payment may appear to be the cause.
However, timing alone does not prove why a bank imposed a restriction.
The bank may have identified unusual activity, received a complaint about a connected transaction, or acted on an instruction from a law enforcement agency.
Without access to the bank’s records, we cannot determine which explanation applies to this particular case.
For ReddyBook readers, the main lesson is that a withdrawal notification and a bank freeze are two different events. Understanding the connection requires information from the bank or the authority responsible for the restriction.
Why the ₹583 Amount Attracts Attention
Most people associate frozen bank accounts with large transfers or serious financial disputes. A restriction following a payment of ₹583 can therefore seem surprising.
However, a small payment may form part of a longer transaction trail.
Banks and investigators may examine where money came from, which accounts handled it, and whether any part of the transaction chain is connected with a reported financial crime.
A payment does not become suspicious simply because it is small. Equally, a small amount does not guarantee that it will be excluded from a financial review.
For ReddyBook users, this distinction is important when trying to understand why an account has been restricted.
What Does It Mean When a Bank Account Is Frozen?
A frozen bank account is an account on which certain transactions have been restricted.
The exact restriction can vary.
Some account holders may be unable to transfer or withdraw money. Others may face a hold on a particular amount while the rest of the balance remains available.
In some situations, the bank may request additional information before restoring normal access.
For ReddyBook readers, the word frozen should not be treated as a complete explanation.
We need to know what type of restriction the bank has applied.
A temporary security block is different from a lien on a disputed amount or a restriction imposed under an official investigation.
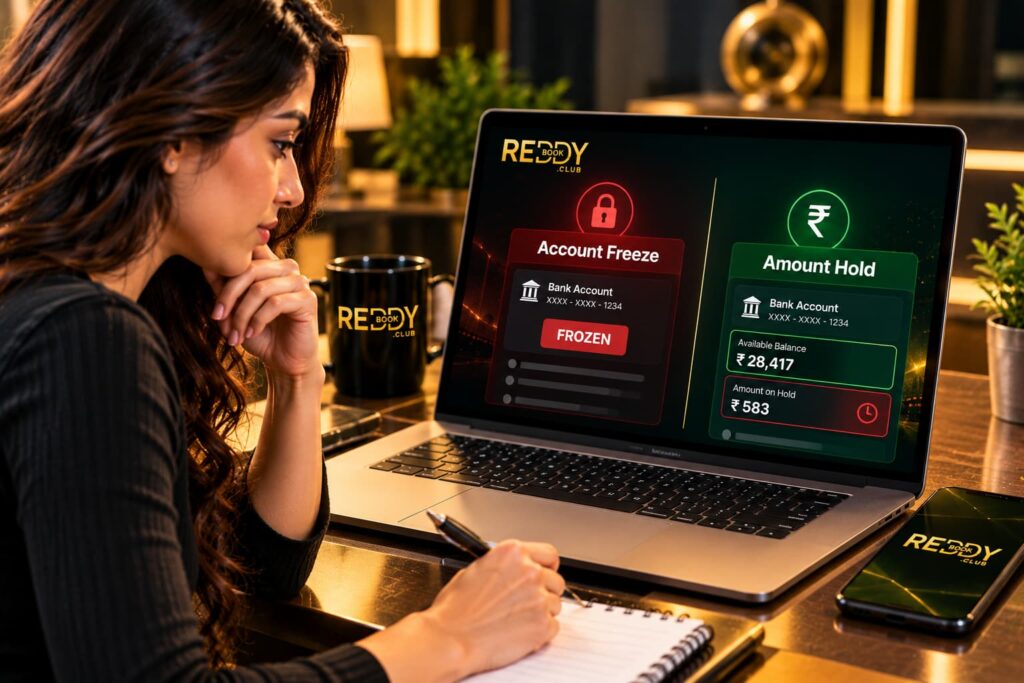
Difference Between an Account Freeze and an Amount Hold
An account freeze may restrict withdrawals or other transactions from the account.
An amount hold, sometimes described as a lien, may apply to a specific sum.
For example, a bank might restrict a disputed amount while allowing other transactions, depending on the instructions and circumstances.
These are not interchangeable situations.
For ReddyBook users, asking the bank to explain the exact restriction can prevent confusion.
The bank should be approached through its verified customer service channels or branch.
Why Can a Small Withdrawal Lead to a Bank Review?
A bank may review transactions for several reasons, including suspected fraud, unusual payment patterns, compliance requirements, or a complaint received through an authorised channel.
A transaction may also be connected to another account that is already under investigation.
For example, a payment received from a third party could later be examined if that third party’s account becomes part of a fraud complaint.
This does not automatically mean that every recipient knew about or participated in wrongdoing.
It means the transaction may need further examination.
For ReddyBook readers, we should avoid assuming that a bank restriction proves guilt.
A review is a process for checking facts, and its outcome depends on the available evidence.
Why the Source of Funds Matters
When money moves between accounts, its source can be important.
Banks may need to understand the origin of certain payments, particularly when there are concerns about fraud or money laundering.
If funds move through several accounts, investigators may attempt to trace the transaction history.
A small incoming payment can therefore attract attention because of its connection to another transaction, not simply because of the amount received.
For ReddyBook users, a withdrawal shown as successful on a gaming platform does not establish how the payment was processed through the banking system.
The underlying transaction details matter.
Could a ReddyBook Withdrawal Be Connected to a Cybercrime Complaint?
One possible reason for a bank restriction is a complaint about a transaction connected with suspected cybercrime.
In India, banks may receive instructions relating to financial fraud investigations.
These instructions can involve disputed funds or accounts that appear in a transaction trail.
However, we cannot confirm that a cybercrime complaint was involved in the reported ₹583 ReddyBook case.
For ReddyBook readers, it is important to distinguish a possible explanation from a verified fact.
A bank freeze should not automatically be described as a cybercrime action unless the bank or relevant authority confirms that connection.
How Transaction Trails Can Affect Account Holders
A transaction trail records how funds move between accounts.
Investigators may examine these records when looking into suspected financial fraud.
If money passes through several accounts, more than one account may appear in the review.
However, appearing in a transaction trail does not by itself establish criminal responsibility.
For ReddyBook users, the important issue is whether the bank has identified a specific transaction, complaint, or legal instruction.
That information can help determine the appropriate next step.
Does a Successful ReddyBook Withdrawal Mean the Payment Is Safe?
A successful withdrawal message generally indicates that a platform has marked a payment as completed or processed.
It does not necessarily establish that every later banking review has been completed.
A bank may still examine an incoming transaction under its own procedures.
For ReddyBook readers, this is an important difference.
A payment status shown on a website is not the same as an official confirmation that the source of funds is free from dispute.
We should also avoid assuming that a withdrawal receipt proves the platform is legally authorised.
Payment processing, account security, and legal compliance are separate questions.
Why Payment Screenshots Are Not Enough
Screenshots can help document what a user saw on a platform.
They may show a payment amount, date, or transaction status.
However, screenshots alone may not establish the actual source of the funds or the reason for a bank restriction.
For ReddyBook users, bank statements and official transaction references may provide more useful evidence.
A screenshot can support an explanation, but it should not replace verified banking records.
ReddyBook ID and the ₹583 Withdrawal Record
A ReddyBook ID may be used to identify an account associated with the platform.
If a user is trying to understand a disputed withdrawal, an account identifier may help organise their own records.
However, an account ID is not proof that a payment was lawful or that the bank must remove a restriction.
For ReddyBook readers, account information should be handled carefully.
We should avoid sharing passwords, verification codes, or full banking details with unknown people who claim they can resolve a freeze.
The relevant records may include the transaction date, amount, payment reference, and any messages received about the withdrawal.
These details can help explain the sequence of events without exposing unnecessary private information.
ReddyBook Login and Access to Payment History
The phrase ReddyBook Login relates to accessing an existing account.
A user who can still access their account may be able to review whatever transaction history the service provides.
However, the current ReddyBook interface and its payment-history features have not been independently verified.
For ReddyBook readers, we should not assume that a particular menu or download option exists.
If a user has already saved payment records, those records may help when speaking with the bank.
However, we should avoid entering account credentials into unfamiliar websites that promise to recover frozen funds.
A fake support page can create another security problem while the original banking issue remains unresolved.
Why Account Access and Bank Access Are Different
A ReddyBook account may remain accessible even when a linked bank account is restricted.
Likewise, a bank account may function normally while a platform account has its own limitations.
These systems operate separately.
For ReddyBook readers, it is important to identify exactly where the problem exists.
If the restriction is imposed by the bank, changing a platform password or opening another gaming account will not remove the banking restriction.
ReddyBook Account Details and Bank Verification
A ReddyBook Account may contain account-related records or personal details.
However, we cannot confirm which information ReddyBook currently collects or stores.
If a bank is reviewing an incoming payment, it may ask the account holder to explain the transaction.
The bank may request relevant records through its normal verification process.
For ReddyBook readers, it is important to respond through verified banking channels rather than unfamiliar agents.
We should not send identity documents to unknown individuals who promise to remove a freeze quickly.
Any request for sensitive information should be checked carefully before a response is provided.
What Should a User Do After Discovering a Bank Freeze?
The first step is to understand the restriction.
An account holder can contact the bank through its official customer service number or visit the branch.
The bank may be able to explain whether the restriction is a security block, an amount hold, or an instruction connected with an investigation.
For ReddyBook readers, it is useful to ask for the available written details of the restriction.
These may include the date, the amount affected, the relevant transaction reference, and any complaint or authority reference the bank is permitted to disclose.
If the restriction comes from a law enforcement instruction, the bank may not have the authority to remove it independently.
Why Written Information Is Helpful
Verbal explanations can be misunderstood or forgotten.
Written information makes it easier to understand what has happened.
It may also help an account holder seek legal advice or follow up with the correct authority.
For ReddyBook users, keeping a clear record of communications can reduce confusion.
We should record the dates of bank visits, complaint numbers, and official responses.
However, personal banking records should not be posted publicly or shared with unverified support accounts.
Can the Bank Unfreeze an Account Immediately?
There is no universal timeline for removing a bank freeze.
The answer depends on why the restriction was imposed.
A temporary security block may be resolved after the bank completes its checks.
A restriction linked to an investigation may require further action by the relevant authority or a court.
For ReddyBook readers, promises of immediate account restoration should be treated cautiously.
No outside agent can reliably guarantee that a bank will remove a lawful restriction within a fixed number of hours.
The correct process depends on the facts and the authority responsible.
Why a Bank May Need Further Instructions
Banks sometimes act on instructions received from authorised agencies.
In such situations, branch staff may not be able to remove the restriction simply because the account holder requests it.
Additional documents or instructions may be required.
For ReddyBook users, this can be frustrating, especially when the disputed amount is small.
However, the size of the transaction does not automatically determine the legal process.
What If the User Did Not Know the Payment Source?
A user may receive money without knowing the full path it followed before reaching their account.
This can happen with many kinds of digital payments.
If a bank later reviews the transaction, the account holder may need to explain the circumstances in which the funds were received.
For ReddyBook readers, the best approach is to provide accurate information and avoid speculation.
We should not invent an explanation or submit documents that do not reflect the actual transaction.
If the matter involves a formal investigation, advice from a qualified lawyer may be appropriate.
Why We Should Not Move Money to Avoid a Freeze
When an account is under review, attempting to hide funds or move money to avoid a restriction can create additional problems.
The appropriate response is to understand the bank’s instructions and cooperate through lawful channels.
For ReddyBook users, opening another account solely to bypass an active restriction is not a reliable solution.
It may also complicate the explanation of the original transaction.
ReddyBook Registration and Payment Identity Questions
The term ReddyBook Registration relates to creating an account associated with the platform.
A user may assume that completing registration or providing personal details makes all later payments secure.
However, account registration does not guarantee that a payment will never be reviewed.
For ReddyBook readers, identity verification and transaction compliance are separate matters.
Even where a platform carries out identity checks, a bank may still examine incoming funds under its own obligations.
We should also avoid assuming that completing a gaming platform’s registration process establishes legal authorisation.
The status of the operator and the source of payments must be considered independently.
ReddyBook App and Withdrawal Notifications
The phrase ReddyBook App may appear in searches about mobile access and payment notifications.
However, the current official availability and features of any dedicated ReddyBook application have not been independently verified.
For ReddyBook readers, a notification saying that a withdrawal is complete should not be treated as proof that no banking issue can arise later.
A platform message reflects information within that service.
A bank’s account restriction is governed by separate systems and procedures.
If a mobile application asks users to pay a fee to unlock a frozen bank account, that claim should be treated with serious caution.
Why Fake Bank-Unfreeze Messages Are Dangerous
Fraudsters sometimes exploit situations where users are worried about blocked accounts.
They may claim to represent a bank, payment provider, or platform support team.
A message may ask for an OTP, banking PIN, or transfer described as a verification fee.
For ReddyBook readers, these requests should not be trusted without independent verification.
Banks and legitimate authorities should be contacted through their published official channels.
ReddyBook Download Links and Payment Recovery Claims
A ReddyBook download link may appear in messages offering help with payment problems.
However, installing unfamiliar software will not remove a bank restriction imposed by a financial institution or authority.
Some fraudulent applications may attempt to collect credentials or access sensitive device information.
For ReddyBook users, a bank-freeze situation is not a reason to install an unverified APK.
We should also avoid applications claiming to provide guaranteed access to frozen money.
The correct resolution depends on the bank’s explanation and the relevant legal process.
ReddyBook Sports Betting and Transaction Risk
The phrase ReddyBook Sports Betting is associated with searches about online gaming activity.
Transactions connected with real-money gaming may raise questions about the operator, payment source, and applicable law.
For ReddyBook readers, it is important to understand that an online platform processing a withdrawal does not establish that its services are legally authorised.
Indian law places restrictions on online money games and related activities.
The precise legal consequences depend on the applicable law and the facts of the transaction.
A bank restriction should not automatically be interpreted as proof that the account holder committed an offence.
However, concerns about payment sources and legal compliance should be taken seriously.
ReddyBook Betting and the Risk of Third-Party Payments
ReddyBook Betting is another term that may appear in online searches about the platform.
Some gaming-related payment systems may involve third-party payment arrangements.
However, we cannot confirm how the specific ₹583 payment was processed.
For ReddyBook readers, this uncertainty matters.
If money arrives from an unfamiliar personal account rather than an identifiable business payment source, questions may arise about its origin.
That does not automatically mean the transfer is fraudulent.
It does mean the payment trail may require closer examination.
We should not assume that the name shown on a gaming platform and the name of the bank sender will always match.
ReddyBook Casino and Withdrawal-Related Claims
The ReddyBook casino category may appear in searches about gaming features and withdrawals.
However, we cannot confirm whether the reported ₹583 transaction came from a casino-related activity, sports activity, or another source.
For ReddyBook readers, the distinction matters because the actual transaction history is more useful than assumptions about the platform’s advertised categories.
A bank reviewing a payment may focus on the source and movement of funds rather than the label displayed on a website.
We should therefore avoid inventing details about how the withdrawal was generated.
Does a ₹583 Bank Freeze Mean the User Has Committed a Crime?
No. A bank restriction does not, by itself, prove that an account holder committed a crime.
An account may be restricted during a review or because it appears in a transaction trail.
The reasons and legal consequences depend on the evidence.
For ReddyBook readers, it is important not to confuse suspicion, investigation, and a finding of wrongdoing.
These are different stages and concepts.
A person facing a restriction should seek accurate information from the bank and, where necessary, qualified legal advice.
Why the Exact Reason Matters
A freeze caused by an ordinary security check may require a different response from one imposed during a formal investigation.
The account holder needs to know which situation applies.
For ReddyBook users, guessing about the cause can lead to unnecessary anxiety or ineffective action.
The most useful information comes from official records and direct communication with the relevant institution.
Can a User File a Complaint About a Frozen Bank Account?
An account holder can raise a complaint with the bank if they believe the restriction has been applied incorrectly or has not been explained adequately.
Banks generally have grievance processes for customer complaints.
If the issue concerns banking service or complaint handling, the Reserve Bank of India’s Integrated Ombudsman framework may be relevant after the bank’s complaint process, subject to its eligibility rules.
However, an Ombudsman complaint does not automatically override a lawful restriction imposed by an investigating authority.
For ReddyBook readers, the appropriate route depends on whether the dispute concerns the bank’s service or an external legal instruction.
Where an investigation is involved, qualified legal advice may be necessary.
How Long Can a Bank Account Remain Frozen?
The duration of a bank restriction depends on its cause.
A security-related hold may be resolved after verification.
A restriction linked to a complaint or investigation may last longer.
There is no reliable fixed timeline that applies to every ₹583 transaction or every ReddyBook-related payment.
For ReddyBook readers, websites promising account restoration within a guaranteed period should be treated cautiously.
The responsible bank or authority is better placed to explain the current status.
If the restriction continues without a clear explanation, the account holder may need to follow the bank’s complaint procedure or seek legal advice.
Read more : Bank account permanently frozen
Why This ₹583 ReddyBook Case Matters to Other Users
The reported scenario highlights how a small online payment can become connected with a much larger concern.
The amount itself does not explain why an account was restricted.
We need to understand the payment source, transaction history, bank procedures, and any official instructions.
For ReddyBook readers, the case also shows why withdrawal screenshots and platform notifications are not enough to establish the full story.
A payment can appear successful while a separate banking issue remains unresolved.
We should not assume that every withdrawal will cause a freeze.
Equally, we should not dismiss a restriction simply because the payment amount is small.
What We Can Learn From the Reported ReddyBook Withdrawal Case
The most important lesson is that banking restrictions require verified explanations.
If a user discovers that their account is frozen after a ₹583 ReddyBook withdrawal, the first question should be why the bank imposed the restriction.
We should not assume that the withdrawal itself was the confirmed cause.
The bank may be carrying out a security review, responding to a complaint, or following an official instruction.
For ReddyBook readers, keeping accurate transaction records and communicating through verified channels can help clarify the situation.
We should also avoid fake recovery agents, unverified APK files, and requests for passwords or banking verification codes.
If the matter involves a formal investigation, professional legal advice may be important.
Understanding the Bigger Picture Behind a Frozen Bank Account
A frozen bank account can be stressful, especially when the amount involved appears small.
The reported ₹583 ReddyBook withdrawal case raises useful questions about digital payments, transaction trails, banking reviews, and account safety.
However, without verified primary records, we cannot establish the exact reason for the reported restriction or conclude that ReddyBook caused it.
For ReddyBook readers, the safest approach is to focus on facts rather than assumptions.
A successful withdrawal message does not guarantee that a bank will never review the payment. At the same time, a bank freeze does not automatically prove wrongdoing.
Understanding the type of restriction, preserving accurate records, and seeking information through official banking and legal channels are the most useful ways to approach such a situation.
The wider lesson is simple: when online payments and banking restrictions become connected, reliable documentation matters far more than the size of the transaction.
FAQs – Bank Account Frozen After a ₹583 ReddyBook Withdrawal
1. Why was a bank account frozen after a ₹583 ReddyBook withdrawal?
A bank account may be restricted because of a transaction review, suspected fraud, a complaint or instructions from an authority. However, the exact reason for the reported ₹583 case has not been independently verified.
2. Can a bank account be frozen for receiving just ₹583?
Yes. A bank restriction is not always based on the amount received. Even a small payment may be examined if it appears in a disputed transaction trail or is linked to an official investigation.
3. Does a ReddyBook withdrawal automatically cause a bank account freeze?
No. There is no evidence that every ReddyBook withdrawal causes a bank freeze. Restrictions depend on the specific transaction, banking procedures and any relevant complaints or legal instructions.
4. What is the difference between an account freeze and an amount hold?
An account freeze may restrict withdrawals or other transactions from the account. An amount hold generally blocks a specific sum while other funds may remain available, depending on the circumstances.
5. Can a bank freeze an account because of a cybercrime complaint?
Yes. Banks may restrict accounts or particular funds when responding to lawful instructions connected with cybercrime investigations. However, a freeze does not automatically prove that the account holder committed an offence.
6. How can we find out why a bank account was frozen?
We should contact the bank through its official customer service channels or visit the branch. The bank may explain the type of restriction and provide available transaction, complaint or authority references.
7. What should we do immediately after discovering a bank freeze?
We should confirm the restriction with the bank, preserve relevant transaction records and request available written details. We should avoid unknown agents who promise immediate account restoration.
8. Can a frozen bank account be unfrozen?
Yes, restrictions may be removed once the applicable requirements are satisfied. The process depends on whether the restriction was imposed by the bank or under an instruction from an authorised agency.
9. How long does it take to unfreeze a bank account in India?
There is no fixed timeline for every case. A temporary security restriction may be resolved after verification, while a restriction connected with an investigation may require additional time or official instructions.
10. Does a successful ReddyBook withdrawal mean the payment is safe?
Not necessarily. A successful withdrawal status may show that a platform processed a payment, but it does not guarantee that the receiving bank will never review the transaction.